NSW court extends Bathla Group voluntary administration to September 2026 as Sydney developer's $3.4bn debt mounts
HouGarden Australia, 18 September — Bathla Group, a Sydney-based developer with a project portfolio valued at A$4.9 billion, entered voluntary administration last month carrying approximately A$3.4 billion in total debt owed to creditors across 219 development sites. The Supreme Court of New South Wales has now extended the convening period — the statutory deadline by which the second meeting of creditors must be held — from its original date to 13 September 2027, giving administrators up to 12 months to work through the company's active construction pipeline in an orderly way.
Voluntary administration is a formal process under Australian corporations law designed to give a financially distressed company breathing space to restructure or to maximise the return to creditors. It differs from liquidation: the aim is to preserve value in ongoing projects rather than wind them up immediately. The extension does not mean construction deadlines have been moved; it means the creditors' meeting at which the company's future will be decided can be deferred until next September at the latest.
Administrator Stephen Longley of international advisory firm Teneo described the scale of the task facing his team. 'We have taken a cautious approach to the timeframe to ensure there is sufficient time to progress and complete projects in an orderly way,' he said. 'The extension gives us the time needed to progress projects towards completion, but that outcome remains dependent on securing further lender support to maintain critical central functions at Bathla. Locking in this funding is therefore an immediate priority and discussions are continuing.'
The court order is explicitly conditional: the extension applies only if administrators are able to obtain further funding from lenders to sustain operations. That arrangement has not yet been finalised, meaning the extended timeline cannot be treated as a certainty. Longley has also noted that the September 2027 date is a ceiling, not a fixed endpoint — he retains the option to call the second creditors' meeting earlier if circumstances permit.
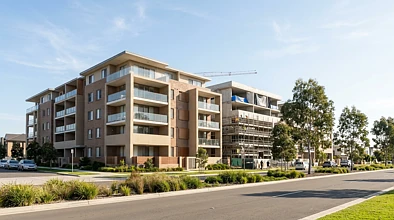
The breakdown of Bathla's A$3.4 billion in liabilities shows the dominant exposure sits with secured lenders at A$3.08 billion. The Australian Taxation Office is owed A$145 million, land tax liabilities amount to A$42 million, other unsecured creditors are collectively owed A$130 million, and employee entitlements total A$4 million. Bathla's projects span residential and mixed-use developments across Sydney.
Before the court order was granted, Longley had negotiated a confidential short-term funding agreement with five lenders to maintain limited operations for two weeks. That followed the standing-down of 213 of Bathla's 350 staff shortly after the group entered administration last month.
Two ASX-listed lenders have separately disclosed their positions. Non-bank lender 360 Capital Group (ASX: TGP) has appointed receivers — a separate role from the administrators — across 162 Bathla-linked properties, representing A$31.7 million in exposure. Receivers act on behalf of secured creditors and operate independently of the administrators appointed to manage the broader company. Diversified fund manager Centuria Capital Group (ASX: CNI) has disclosed a direct exposure of A$4.5 million to Bathla, but has not appointed receivers.
Bathla Group is an Australian company and its administration has no direct bearing on the New Zealand property market. However, the case illustrates the risks that can materialise in large, highly leveraged development groups, a consideration relevant to any cross-border investor assessing exposure to Australian residential development finance.